Breaking News
 America could descend into chaos in minutes: Ex-FBI agents warn of 'existential threat'...
 Ominous new war signal as Trump sends third aircraft carrier toward Iran as he threatens...
 UFOs could be hiding in our oceans, says retired US Navy admiral... as researcher claims to have...
 Seattle's Socialist Mayor Faces Business Revolt As Utopia Dreams Implode, Nearly Half Weigh Exit
Top Tech News
 Microreactor Gets DOE Approval for Full Power Testing, Previously Contracts with Army...
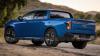 Ford Fathom: Everything We Know About The Sub-$30,000 Affordable EV Truck
 Love it or loathe it, AI is birthing a golden age of science
 SpaceX has no competition -- Saurav Shroff, Starpath
 Living computers forge a 'hive mind' and work together to outsmart AI
 The Faraday duffle bag: A digital lifeline in a surveillance-saturated world
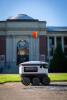 Delivery Robots Accused Of Scanning Customers' Faces, Sharing Biometric Data
 Brace Yourselves: Serious Trouble Brewing In The Data Center Industry
 FDA-Approval for Drill-Free Cavity Care May Be Imminent After Great Phase 3 Treatment Trial
 California Startup Says It Has Injected AI-Designed Virus Into Humans For First Time
Large Banks' Total Exposure to Commercial Real Estate
The MBA estimates that $875 billion of commercial and multifamily mortgages mature in 2026, and many of these loans must be refinanced at much higher rates than when they were made.
I have calculated the total CRE exposure (CRE nonfarm-nonresidential and multifamily mortgages, CRE construction loans, CRE loans not secured by real estate, and unused CRE commitments) as a percentage of total equity as a broad measure of bank exposure to commercial real estate. A variation of this ratio is used by banking regulators to assess CRE exposures; any ratio over 300% is viewed as excessive exposure to CRE.
Data are as of March 31, 2026 (Q1).
Below is a list of the total CRE exposure of the 50 banks with more than $10B in assets where their exposure exceeds 300% of total equity capital (50 out of 154 large banks, 4,336 banks of any size). Two have exposures greater than 500% of equity, and 14 have exposures greater than 400%. In Q4, the comparable numbers were 52, five and 17.
Most prominent (by size) are #7 Flagstar Bank, #22 Valley National Bank, #29 Columbia Bank (formerly Umpqua Bank), #30 Zions Bancorporation, #43 SouthState Bank, #44 East West Bank, and #48 Old National Bank, each of which has more than $50B in total assets.
Some of the drop in the large-bank list comes from mergers rather than lower exposures. Synovus (369% in Q4) merged into Pinnacle Bank on Jan. 2, and Comerica (302% in Q4) merged into Fifth Third in early February. EagleBank (520% in Q4) fell off the list because its assets slipped below $10B; its exposure is still 473%. FirstBank of Colorado (392% in Q4) dropped to 158% after PNC acquired it in January, because purchase accounting pushed down to the bank more than doubled its equity.